A sudden shortage of money can make a quick loan look like the easiest solution. Maybe your salary is still a few days away, an urgent bill has arrived, or an unexpected expense needs immediate attention.
This is when many people start searching for short term loan apps that promise a fast application and quick disbursal.
But speed should not be the only reason to choose a loan.
A small borrowing decision can become expensive if you do not check the lender, repayment date, interest cost, processing charges, and loan terms before accepting the offer.
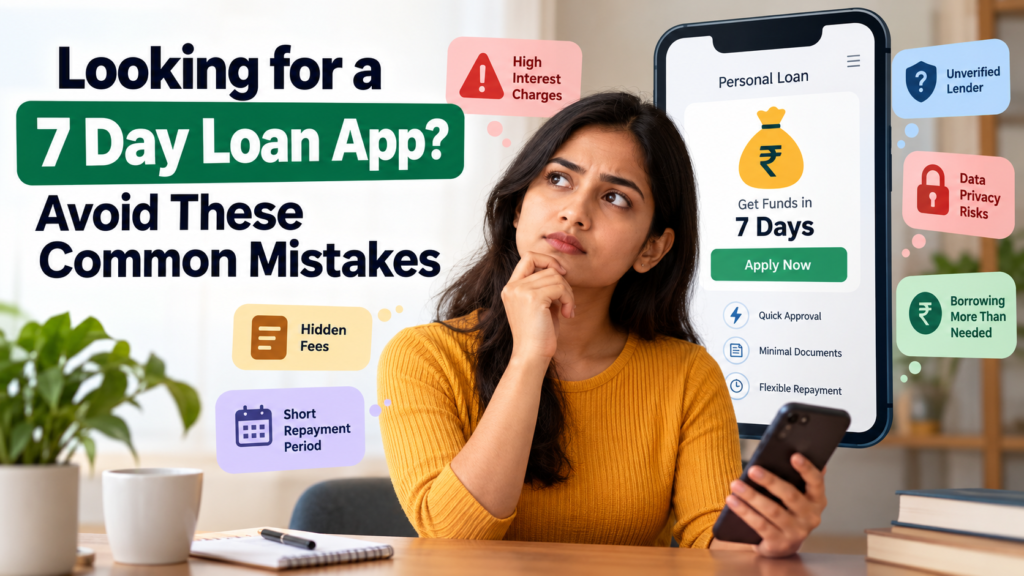
If you are considering a short term digital loan, here are the common mistakes you should avoid.
Mistake 1: Choosing an App Only Because It Offers Fast Money
Getting money quickly sounds attractive during an emergency, but fast approval does not automatically mean a loan is suitable for you.
Some borrowers apply without checking how much they will actually receive or how much they must repay.
Instead of focusing only on approval speed, check the full loan offer.
Look at the loan amount, total repayment amount, interest cost, processing fee, repayment period, and due date.
A loan that takes a few extra minutes to understand is better than accepting an expensive loan in a hurry.
Mistake 2: Not Checking Who Is Actually Providing the Loan
One of the most important things to understand is that the app name and lender name may not always be the same.
A digital lending app may work with a bank or a Non Banking Financial Company that actually provides the credit.
Before borrowing, check who the regulated lender is.
RBI advises borrowers to verify whether a digital lending app is associated with an RBI regulated bank or NBFC by checking the lender’s official website. It also advises users to avoid loan apps received through suspicious SMS or social media links.
If the lender details are difficult to find, do not rush into the application.
Mistake 3: Looking Only at the Loan Amount
Suppose an app says you are eligible for ₹10,000.
It is easy to think that ₹10,000 is the only number that matters.
But you should also check how much money will actually reach your bank account and how much you need to repay.
For example, certain disclosed charges may affect the final amount received or the overall borrowing cost.
Always compare these three figures:
The approved amount.
The amount credited to your bank account.
The total amount you must repay.
This simple comparison can help you understand the loan more clearly.
Mistake 4: Ignoring the Total Cost of Borrowing
A loan should never be judged only by an advertisement showing a low interest rate.
There may be other costs involved.
These can include interest, processing charges and applicable taxes.
RBI’s digital lending framework requires regulated lenders to provide borrowers with information about the all inclusive cost of a digital loan through the Annual Percentage Rate, commonly known as APR.
Check the Key Fact Statement and loan agreement before accepting the offer.
If you do not understand how much the loan will cost, do not confirm it until the terms are clear.
Mistake 5: Borrowing the Maximum Amount Offered
Loan apps may show that you are eligible for more money than you originally planned to borrow.
That does not mean you should take the full amount.
Eligibility and affordability are different things.
For example, you may be eligible for ₹20,000 but only need ₹6,000 for an urgent expense.
Borrowing the extra ₹14,000 without a genuine reason increases the amount you need to repay.
A useful rule is simple.
Borrow according to your need and repayment capacity, not according to the maximum limit displayed on the screen.
Mistake 6: Forgetting to Check the Repayment Date
For a short term loan, the repayment date is especially important.
Imagine your salary comes on the 10th of every month but your loan repayment is due on the 7th.
Even if your monthly income is enough to repay the loan, the timing can create a cash flow problem.
Before borrowing, check exactly when repayment is due.
Compare that date with your salary, business income, or other reliable source of money.
Do not depend on uncertain income to repay a short duration loan.
Mistake 7: Taking Another Loan to Repay the First Loan
This is one of the most dangerous habits in short term borrowing.
A person takes one loan, cannot repay it on time, then takes another loan to pay the first one.
Soon, multiple repayment dates and borrowing costs can become difficult to manage.
A short term loan should ideally solve a temporary cash gap.
It should not create another loan requirement.
Before borrowing, ask yourself:
Can I repay this loan from my expected income without taking another loan?
If the answer is no, reconsider the amount or look for another solution.
Mistake 8: Giving Unnecessary Phone Permissions
Digital loan applications require certain information to process applications and service loans, but borrowers should still pay attention to app permissions and privacy.
RBI guidance says data collection by regulated digital lenders should be need based and collected with the borrower’s prior and explicit consent. Digital lending apps should also have a clear privacy policy.
Before installing or using an app, check what permissions it requests.
Do not casually give access to personal information that appears unrelated to the loan process.
You should also never share your OTP, UPI PIN, debit card PIN, or internet banking password with anyone claiming to help approve your loan.
Mistake 9: Applying to Many Apps at the Same Time
When someone needs money urgently, applying to several apps may feel like a way to improve the chance of approval.
But this can make borrowing harder to manage.
You may receive multiple offers with different interest rates, repayment dates, and charges. If more than one loan is accepted, your monthly obligations can increase quickly.
Instead, first decide how much you genuinely need.
Then compare a limited number of suitable options and read their terms carefully before proceeding.
If you are researching available options, you can start with this 7 Days Loan App List and then independently verify the lender and loan terms before applying.
Mistake 10: Using Short Term Loans for Regular Lifestyle Expenses
A short term loan may sometimes help with an unexpected emergency, but repeatedly borrowing for shopping, entertainment, food delivery, subscriptions, or other lifestyle expenses can create a financial problem.
If you regularly need a loan before your next salary, the issue may not be temporary.
Your monthly budget may need attention.
Review your essential expenses, EMIs, subscriptions, discretionary spending, and savings.
Reducing even a few recurring expenses can sometimes remove the need for repeated small loans.
What Should You Check Before Accepting a Loan?
Before pressing the final acceptance button, take a few minutes to review everything.
Confirm the name of the actual lender and check whether it is a regulated bank or NBFC.
Read the Key Fact Statement.
Check the amount you will receive.
Understand the APR and other disclosed charges.
Confirm the total repayment amount.
Check the repayment date.
Read the privacy policy.
Check customer support and grievance details.
Make sure you can repay the loan from your regular income.
RBI guidance also requires important loan information and grievance related details to be made available to borrowers through regulated digital lending arrangements.
Think About Alternatives Before Borrowing
A loan is not always the first solution to a seven day money shortage.
Depending on the situation, you may be able to use emergency savings, postpone a non essential purchase, request additional time for a payment, or ask your employer whether a salary advance facility is available.
These alternatives will not work in every situation, but checking them before borrowing can save money.
Credit is most useful when it solves a real temporary need and you already know how you will repay it.
Final Thoughts
A 7 day loan app can appear convenient when money is urgently required, but convenience should never replace careful decision making.
Do not choose an app only because it promises quick cash.
Check the lender behind the platform, understand the full borrowing cost, read the repayment terms, protect your personal information, and borrow only what you genuinely need.
The most important question is not how quickly you can receive the loan.
It is whether you can repay it comfortably without creating another financial problem.
Taking ten minutes to check the details today can save you from weeks or months of unnecessary financial stress later.