In today’s financial landscape, the ability to leverage existing assets has become crucial for individuals and businesses alike. One of the popular means of accessing quick funds is through a Loan Against Property (LAP). This financial product allows borrowers to unlock the value of their real estate while retaining ownership. In this article, we will explore what a Loan Against Property is, how it works, its advantages, the interest rates involved, and essential factors to consider before opting for this type of loan.
What is a Loan Against Property?
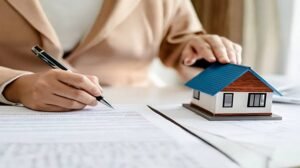
A Loan Against Property is a secured loan where borrowers pledge their residential or commercial property as collateral to lenders, typically banks or financial institutions. It is an excellent option for those in need of significant funds for various purposes, such as business expansion, education, medical expenses, or debt consolidation.
How Does it Work?
When you apply for a Loan Against Property, the lender assesses the value of your property, which determines the loan amount you are eligible for. Generally, you can borrow up to 60–70% of the property’s market value. The process typically involves the following steps:
1. Application
You fill out the loan application form and submit required documents, including property proof, income proof, and identity verification.
2. Verification
The lender conducts a thorough verification process. This may include a valuation of the property and verifying your creditworthiness.
3. Loan Processing
Once approved, the lender disburses the loan amount. The borrower must repay the amount along with interest over a specified tenure, usually ranging from 5 to 15 years.
4. Collateral
Throughout the loan tenure, the property stays mortgaged to the lender. If the borrower defaults on repayments, the lender has the right to seize the property.
Advantages of Loan Against Property
1. Larger Loan Amounts
Compared to unsecured loans, LAP offers higher loan amounts due to the collateral involved. This makes it suitable for substantial financial requirements.
2. Lower Interest Rates
LAP generally comes with lower interest rates than personal loans or credit cards, making it an attractive borrowing option.
3. Flexible Repayment Schemes
Many lenders offer flexible repayment options, allowing borrowers to choose a tenure and EMI amount that suits their financial capabilities.
4. Usage of Funds
There are no restrictions on how the funds can be utilized. Borrowers have the freedom to use the loan for various purposes, be it personal or professional.
5. Ownership Retained
While the property is mortgaged, the borrower retains ownership and can continue living or operating their business on the property.
Understanding Loan Against Property Interest Rates
Interest rates play a crucial role in determining the cost of borrowing. The interest rates on Loan Against Property can vary significantly based on several factors, including:
1. Credit Score
Borrowers with a strong credit history typically qualify for lower interest rates.
2. Property Location and Type
The type of property (residential or commercial) and its location can influence its market value, subsequently affecting the interest rate.
3. Loan Tenure
Longer tenures may attract higher interest rates, while shorter tenures could offer lower rates.
4. Lender Policies
Different lenders have unique policies, which can lead to variations in offered interest rates.
Generally, the interest rates on LAP can range from 8% to 15% per annum, but it’s essential to shop around and compare offers from multiple lenders to secure the best deal.
Factors to Consider Before Opting for a Loan Against Property
- Repayment Capability: Assess your capacity to repay the loan. Defaulting can lead to losing the collateral property.
- Loan Terms: Scrutinize the loan terms, including interest rates, tenure, processing fees, and other charges.
- Property Valuation: Be aware of the property’s market value as it directly impacts the loan amount.
- Hidden Charges: Look for any hidden fees or penalties associated with early repayment or delayed payments.
- Legal Implications: Ensure that all legal documents related to the property and loan terms are understood and clarified before signing.
Conclusion
A Loan Against Property can be a powerful financial tool that allows individuals and businesses to unlock the equity in their real estate assets. Understanding the nuances of this product, from its benefits to interest rates and essential considerations, can help you make informed borrowing decisions. Whether for personal needs or business objectives, LAP has the potential to provide quick financial relief while maintaining ownership of your property. Always consult with financial advisors or professionals before committing to such significant liabilities and ensure that your repayment plan aligns with your financial situation.
By leveraging the value in your property responsibly, a Loan Against Property can serve as a bridge to reaching your financial goals.