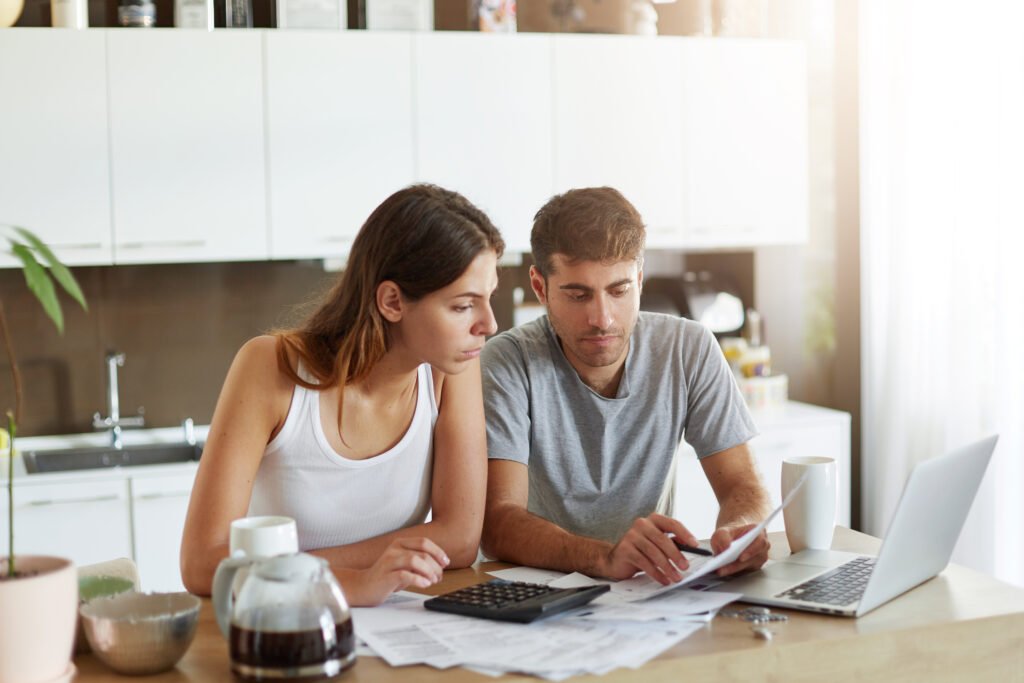
Portrait of serious man and female sitting at kitchen table, dealing with financial issues, holding documents. Family couple calculating their debts while sitting together at kitchen. Business concept
Financial planning can be different for dual-income professional couples because two careers can bring separate salaries, retirement accounts, employee benefits, investments, tax responsibilities, and financial goals into one household.
A financial advisor for dual-income professional couples near Naperville is a relevant planning consideration for households that need to coordinate these different financial areas. Instead of viewing each income, account, or benefit separately, couples can consider how their combined finances affect cash flow, retirement, investments, taxes, insurance, property, and long-term family goals.
Combining Two Financial Lives
When both partners earn an income, each person may have different financial arrangements through work and personal accounts. One partner may have a 401(k), while the other may have a different employer retirement plan. They may also have separate investment accounts, insurance coverage, stock options, or other benefits.
Bringing these details into one household financial picture can reveal areas that deserve attention. For example, both partners may have strong retirement savings but different levels of investment risk. They may also have overlapping insurance coverage in one area while having limited protection in another. Coordinating these details can help create a clearer view of the household’s overall financial position.
Creating a Retirement Strategy for Two People
Couples do not always retire at the same age. One person may continue working while the other begins retirement. Their retirement accounts may also have different balances, contribution levels, and investment choices.
Retirement planning can consider:
- Expected retirement dates
- Current retirement savings
- Social Security benefits
- Employer retirement plans
- Expected retirement income
- Required Minimum Distributions
- Desired retirement lifestyle
Looking at both partners’ retirement resources can provide a clearer picture of how those resources may support future household expenses. Investment decisions can also be connected to retirement timing, risk, income needs, and the length of time assets may need to remain invested.
Bringing Tax Decisions into the Picture
Two professional incomes can create a more detailed tax picture, particularly when a household also has investment income, bonuses, stock compensation, or retirement distributions.
Tax planning may involve reviewing retirement accounts, Roth conversion opportunities, investment income, capital gains, charitable contributions, and the tax effects of major financial decisions. The timing of one financial decision can affect other parts of the household’s finances.
For example, a large retirement distribution may increase taxable income, while selling an appreciated investment may create a capital gain. Considering these effects before making major financial moves can help couples understand the wider financial impact of their choices.
Managing Cash Flow and Competing Goals
Two incomes can support several financial priorities at the same time, but those priorities may compete for available cash. A couple may be paying a mortgage, saving for college, investing for retirement, reducing debt, and maintaining emergency savings.
Cash-flow planning can help determine how current income is being used and whether spending and saving decisions support the couple’s larger goals. It can also help identify how much money is available for investments, debt payments, education costs, or other priorities without losing sight of everyday expenses.
Protecting Household Income
For a professional couple, both incomes may play an important role in maintaining the household’s lifestyle. An unexpected disability, premature death, serious illness, or long-term care need could change the family’s financial position.
Insurance planning may include:
- Life insurance needs
- Disability coverage
- Health insurance
- Long-term care considerations
- Income replacement needs
- Existing policy coverage
The appropriate level of protection depends on factors such as income, debts, dependents, assets, and future obligations. Reviewing both partners’ circumstances can place insurance decisions within the larger financial plan.
Considering Homes in More than One State
Some families have financial connections to multiple states. A couple may own a primary home in Illinois and another property in North Carolina. The second property may be a vacation home, investment property, family property, or a future residence.
For a financial advisor for families with homes in Illinois and North Carolina, this type of household situation can involve several planning areas. Property ownership may affect cash flow, insurance, estate planning, investment decisions, and tax considerations
The exact treatment of property and income can depend on individual circumstances and applicable state and federal rules. Multi-state property can therefore be considered as part of the family’s overall financial picture rather than as a completely separate issue.
Coordinating Investments and Employee Benefits
Dual-income professionals may accumulate wealth through several channels. Retirement accounts, taxable investments, employer stock, stock options, and other workplace benefits can all form part of a household’s assets.
Investment planning can help couples understand how these different assets fit together. Asset allocation, diversification, risk assessment, and investment strategy may all be reviewed based on the household’s goals and time horizon.
Employee benefits can also deserve attention. Two employers may offer different retirement contributions, insurance options, or stock-related benefits. Understanding these benefits together can help couples make more informed decisions about saving and investing.
Reviewing the Plan as Life Changes
A financial strategy can change as careers and family circumstances develop. A promotion, career transition, inheritance, home purchase, new child, business interest, or planned retirement can affect several financial areas at once.
Regular reviews can help couples reassess their income, retirement contributions, investments, insurance, taxes, property, and estate plans. These reviews can also provide an opportunity to adjust financial priorities when household circumstances change.
Final Thought
Dual-income professional couples often manage more than two paychecks. Their financial picture may include multiple retirement accounts, investments, employee benefits, properties, tax considerations, and family goals. Financial advisor for dual-income professional couples near Naperville planning can be viewed within this larger picture, where retirement, investments, cash flow, protection, taxes, property, and family wealth are connected as part of long-term financial planning.